

If you’ve been tracking the markets through 2025 and into 2026, you already know the story sharp rallies followed by sudden corrections, global cues swinging sentiment overnight, and that constant nagging question every investor asks at some point: should I invest a lump sum now, or spread it out through a SIP?
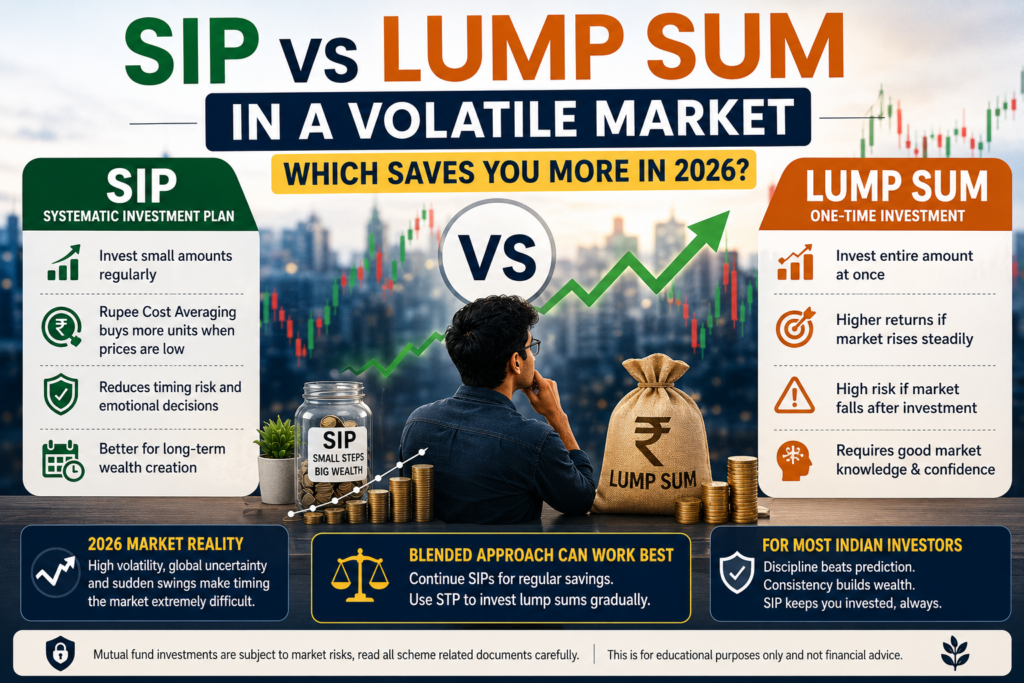
Quick answer: In a volatile market like 2026, SIPs (Systematic Investment Plans) generally offer better protection against timing risk and emotional decision-making, making them the safer choice for most retail investors. Lump sum investing can outperform SIPs when markets are undervalued and set to rise steadily, but it demands precise timing and a stronger risk appetite. For the average investor without deep market expertise, a blended approach usually works best.
Let’s break this down properly, because the “right” answer genuinely depends on your situation, not just market conditions.
What SIP and Lump Sum Actually Mean
Before comparing them, let’s get the basics straight.
A SIP is a method where you invest a fixed amount at regular intervals usually monthly into a mutual fund scheme. Instead of putting in ₹1,20,000 in one shot, you invest ₹10,000 every month for a year.
A lump sum investment means putting your entire investible amount into a fund or stock in one go, right at the start.
Both routes can use the same underlying fund. The difference lies entirely in how the money enters the market, not where it goes.
Why 2026 Is a Genuinely Tricky Year for Timing Decisions
I remember a friend who received his annual bonus in early 2025 and sat on it for three months trying to “time the dip.” By the time he decided to invest, the market had already moved past the point he was waiting for. That hesitation cost him more than any correction would have.
2026 carries similar unpredictability. Interest rate movements, global trade tensions, currency fluctuations, and domestic policy shifts are all playing out at once. Markets are reacting faster than they used to, and corrections that once took weeks now sometimes happen in days.
This is exactly the kind of environment where the SIP versus lump sum debate stops being theoretical and starts affecting real portfolios.
How SIP Works in Volatile Conditions
Rupee Cost Averaging Is the Core Advantage
When you invest a fixed amount regularly, you automatically buy more units when prices are low and fewer units when prices are high. Over time, this averages out your purchase cost, which softens the blow of sudden downturns.
Here’s a simple way to picture it: imagine investing ₹5,000 every month for six months in a fund whose NAV moves like this ₹50, ₹45, ₹40, ₹42, ₹48, ₹55. With a SIP, you end up owning more units bought during the ₹40–45 range than you would have if you’d invested it all at ₹50 on day one. That’s rupee cost averaging quietly working in your favor.
Behavioral Advantage
Volatility doesn’t just test your portfolio it tests your patience. A lot of investors panic-sell during downturns and jump back in only after prices recover, which is the worst possible sequence. SIPs remove a chunk of that emotional decision-making because the investment happens automatically, regardless of what the news headlines say that week.
Where SIP Falls Short
SIPs aren’t magic. If the market moves in a strong, sustained upward trend for an extended period, a SIP can end up with a slightly lower average return than a lump sum invested right at the start, simply because a large part of your money enters the market later and misses some of the early gains.
How Lump Sum Works in Volatile Conditions
The Upside
If you invest a lump sum during a genuine market dip not a minor dip, but a meaningful correction and the market recovers steadily afterward, your returns can outpace a SIP quite comfortably. This is because the entire capital starts compounding from day one instead of gradually over months.
The Real Risk
The catch is obvious: nobody consistently knows when the “bottom” actually is. Even experienced fund managers get this wrong regularly. If you invest a lump sum right before a fresh downturn, your entire capital takes the hit at once, and recovering psychologically from that is harder than most people expect.
I’ve seen investors put in a large sum right after a market rally, convinced it would keep climbing, only to watch a 12–15% correction hit within weeks. The number on paper stings more when it’s your entire investment reacting at once rather than a portion of it.
A Practical Comparison: SIP vs Lump Sum in 2026
| Factor | SIP | Lump Sum |
|---|---|---|
| Timing risk | Low – spread across months | High – depends entirely on entry point |
| Emotional discipline needed | Lower | Higher |
| Best suited for | Salaried individuals, beginners | Investors with market knowledge and idle large capital |
| Performance in rising markets | Slightly lower than lump sum | Higher, if timed well |
| Performance in falling/volatile markets | Generally more stable | Riskier, can amplify losses |
| Liquidity requirement | Small amounts committed regularly | Large amount committed upfront |
Which One Actually Saves You More Money?
This is where most articles give a vague answer, so let’s be direct about it.
If you have a large sum sitting idle say, from a bonus, inheritance, or property sale and you’re not confident about market direction, splitting it isn’t a compromise; it’s a strategy. Many financial planners suggest a STP (Systematic Transfer Plan), where you park the lump sum in a liquid or debt fund and then transfer it gradually into equity funds over 6 to 12 months. This gives you the safety of a debt instrument while still gaining exposure to equity in a phased manner.
For regular income earners investing out of monthly savings, SIP isn’t really a choice it’s simply the natural way to invest, and in a volatile year, it happens to also be the statistically safer one.
For someone who deeply understands market cycles, has a higher risk tolerance, and identifies a genuine undervaluation in the market, a lump sum investment can generate stronger returns. But this isn’t a strategy for someone investing their first ₹50,000.
A Simple Way to Decide for Yourself
Ask yourself these three questions honestly:
- Do I have a steady monthly income to invest, or a one-time large amount? If it’s monthly income, SIP is the natural fit. If it’s a lump sum, consider phasing it in through an STP.
- How would I react if my investment dropped 15% in a month? If that thought makes you anxious, SIP suits your temperament better.
- Do I have the time and knowledge to track market valuations closely? If not, don’t try to time a lump sum entry spread it out instead.
Common Mistakes to Avoid in 2026
- Stopping SIPs during a downturn. This defeats the entire purpose of rupee cost averaging. The dip is exactly when your SIP is buying more units cheaply.
- Investing a lump sum purely based on market hype. A rally in the news isn’t the same as a fundamentally sound entry point.
- Ignoring your own financial goals. Whether you choose SIP or lump sum should also depend on your investment horizon short-term goals need more caution regardless of method.
- Treating this as a one-time decision. You can combine both approaches across different parts of your portfolio depending on when the money becomes available to you.
FAQs
Is SIP always better than lump sum in a falling market? Not always, but generally yes for peace of mind. SIP reduces the risk of investing everything at a bad price point, though a lump sum investment made near the bottom of a fall can outperform SIP once the market recovers.
Can I switch from SIP to lump sum midway? Yes. Many investors run an ongoing SIP and also make occasional lump sum investments when they receive extra funds, like a bonus. There’s no rule against combining both.
What is the safest option for a first-time investor in 2026? For most beginners, starting with a SIP in a diversified equity or hybrid fund is a more comfortable entry point than a lump sum, simply because it limits the impact of any single bad timing decision.
How much should a lump sum investor keep in equity during high volatility? This depends on individual risk appetite and financial goals, but many investors choose to phase a large lump sum into equity over several months using an STP rather than deploying it all at once.
Final Thought
Markets in 2026 aren’t going to stop being unpredictable just because we want them to. What you can control is how disciplined your approach is, not how accurately you predict the next big move. If you’re still unsure where to start, open your investment app today and set up even a small SIP you can always scale it up once you’re comfortable, but starting late costs more than starting small.
Disclaimer: This article is for general informational purposes only and does not constitute financial advice. Mutual fund investments are subject to market risks. Please consult a certified financial advisor before making investment decisions based on your personal financial situation.