For most of us, paying through UPI has become so effortless that we barely think about it anymore. Tea stall, grocery store, cab ride, online shopping scan, pay, done, no charges asked. So when headlines started suggesting that UPI might not stay entirely free, a lot of people understandably got worried. Will your next UPI payment suddenly cost you money?
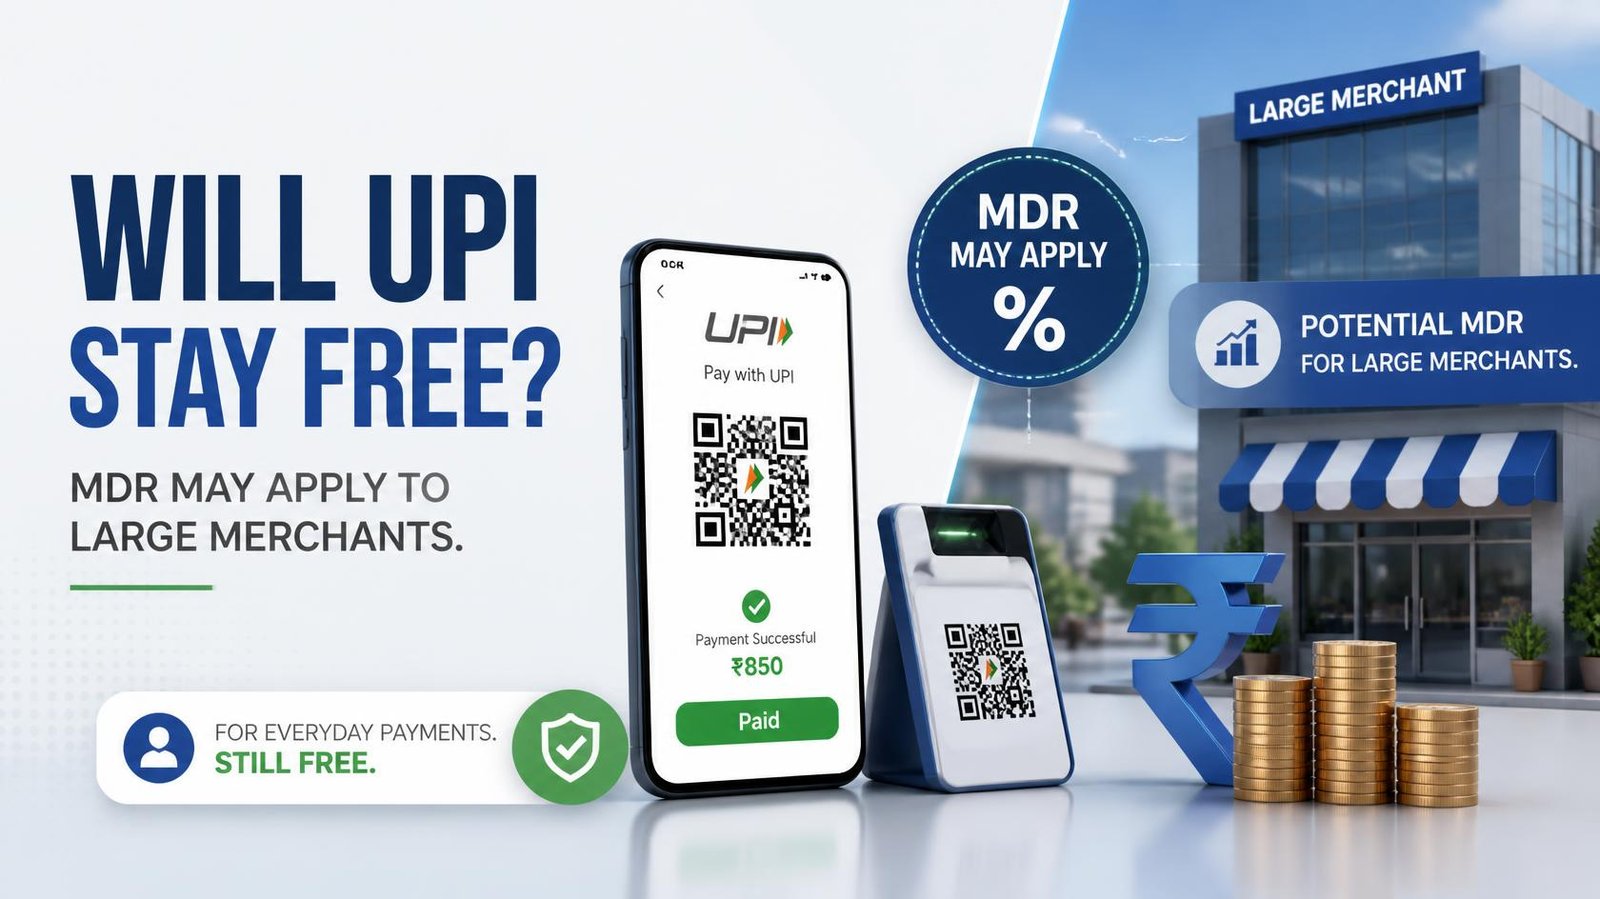
Quick takeaway: For everyday users, UPI is expected to remain completely free. What’s being discussed is a small Merchant Discount Rate (MDR) that could apply only to large merchants crossing a certain annual turnover, not to individual consumers or small shopkeepers. Nothing has been finalised yet, and any final call will come only after the relevant law is amended and a dedicated committee reviews the framework.
What Is MDR, and Why Does It Matter Here?
Merchant Discount Rate, or MDR, is a small fee that a merchant pays to banks and payment service providers every time a customer pays digitally. Think of it as a processing charge the same way a shopkeeper pays a small percentage to a card network whenever someone swipes a debit or credit card.
Before 2020, this fee also applied to UPI and RuPay debit card transactions. Then, in January 2020, the government made MDR zero for both UPI and RuPay debit cards to encourage more people and businesses to adopt digital payments. That single decision is a big reason UPI grew as fast as it did merchants had zero cost to accept it, and customers had zero cost to use it.
Why Is the Government Reconsidering This Now?
Here’s the part that often gets lost in the noise: zero MDR does not mean zero cost. Every UPI transaction still involves banks, servers, fraud detection systems, customer support, and payment infrastructure that all cost money to run. Since merchants and customers aren’t paying anything, someone else has been absorbing that cost.
That “someone” has largely been the government, through annual incentive schemes that reimburse banks and payment companies for a portion of their UPI-related expenses, and the payment companies and banks themselves, who eat the rest.
Industry bodies have pointed out for a while that these government subsidies cover only part of the actual cost of running the UPI ecosystem, not all of it. With UPI now processing an enormous share of India’s digital payment volume, that gap has become harder to ignore. This is essentially the financial sustainability question the current discussion is trying to answer.
What Has Actually Changed Recently
This isn’t just speculation anymore there’s been real legislative movement. Parliament passed an amendment to the Payment and Settlement Systems Act, 2007, which removes the earlier legal bar that prevented banks and payment providers from charging MDR on notified digital payment modes like UPI.
In simple terms, this amendment doesn’t impose a new charge by itself. It removes the legal obstacle that would have prevented one. Whether an MDR is actually introduced, and at what rate, is a separate decision that comes later.
Following the amendment, the Finance Minister publicly clarified that any potential MDR would apply only to merchants, not to end customers making UPI payments. She also noted that the final framework will be decided by the UPI and Services Steering Committee, headed by the National Payments Corporation of India (NPCI), and only after Parliament’s legislative process is complete.
Separately, the Finance Ministry has stated that ordinary UPI users will continue to face no transaction charges, and that if an MDR is introduced, it would apply only to a limited set of merchant transactions above a certain turnover threshold, at a rate described as far lower than typical card MDRs.
Who Might Actually Be Affected
Based on the discussions reported so far, the direction seems fairly consistent:
- Individual users and consumers Expected to remain unaffected. No charge for scanning and paying via UPI.
- Small and mid-sized merchants Also expected to remain outside any new MDR, since the proposals discussed so far target only large businesses.
- Large merchants above a turnover threshold This is where a nominal MDR, reportedly in the range of a few basis points (a fraction of a percent), is being discussed. Different reports have cited slightly different threshold figures, generally somewhere between roughly ₹1 crore and ₹4 crore in annual turnover, so the exact cutoff is still being worked out.
It’s worth remembering that industry associations like the Payments Council of India have, in the past, pushed for a somewhat higher MDR on large-value UPI transactions, so the final number that gets adopted, if any, may differ from any single figure floating around right now.
A Practical Way to Think About This as a Consumer
Imagine you run a small kirana store with an annual turnover of ₹15 lakh, and you accept UPI payments all day. Based on everything discussed so far, this kind of small business is unlikely to see any change you’d keep accepting UPI exactly as you do today, at zero cost.
Now imagine a large retail chain or a big e-commerce platform processing crores of rupees in UPI payments every month. If a nominal MDR is eventually introduced for large merchants, a business like this might pay a small percentage on its UPI transaction volume, similar to what it may already pay on card transactions, just at a much lower rate.
For an everyday shopper walking into either the kirana store or the large retail outlet, the amount you pay at checkout isn’t expected to change either way. That’s the core distinction that keeps getting repeated across every official clarification so far: this is a merchant-side conversation, not a consumer-side one.
Why This Matters for Your Personal Finances
Even though this news is mostly about the businesses accepting your payments, it’s still worth paying attention to, for a few reasons:
- Awareness protects you from misinformation. Whenever policy chatter like this circulates, misleading messages about “UPI charges starting soon” tend to spread quickly. Knowing the actual, verified position helps you avoid reacting to rumours.
- Small businesses you rely on could see cost changes. If you run a business yourself, or depend on local vendors, understanding where the threshold might land helps you gauge whether you’d be affected at all.
- It’s a reminder that “free” services still have real costs somewhere. This is a useful mental model for personal finance in general whether it’s a payment app, a mutual fund with a hidden expense ratio, or a “free” credit card, someone is bearing the cost, and it helps to know who.
What to Watch Out For Next
A few things will tell you how this actually plays out over the coming months:
- Whether the amendment to the Payment and Settlement Systems Act gets finalised through the full legislative process.
- What the NPCI-led steering committee eventually recommends as the exact turnover threshold and MDR rate, if any.
- Whether small merchants and consumers stay excluded, as every official statement so far has promised.
- Any follow-up clarification from the Finance Ministry, since this topic has already triggered rumours and denials once before, back in 2025.
Until an official notification is issued, it’s safe to treat specific numbers circulating online, whether it’s a rate or a turnover cutoff, as provisional rather than final.
This article is for general informational purposes only and reflects publicly reported developments as of the time of writing. It should not be treated as financial, legal, or regulatory advice. Policies around MDR and UPI are still evolving, and readers should verify the latest official updates from the Reserve Bank of India, the Ministry of Finance, or NPCI before making any financial decisions based on this topic.
Frequently Asked Questions
Will I be charged for using UPI as a regular customer? No. Every official statement so far, including from the Finance Ministry and the Finance Minister directly, has confirmed that consumers making UPI payments will not face any transaction charges.
What is the proposed MDR rate for large merchants? Reports have mentioned figures in the range of a few basis points, roughly 0.04% to 0.07% in some accounts, though industry bodies have separately proposed higher rates in the past. No final rate has been officially notified yet.
Which merchants could be affected by the new MDR? Only large merchants above a certain annual turnover threshold are being considered, with various reports citing figures somewhere between roughly ₹1 crore and ₹4 crore. Small businesses and individual shopkeepers are expected to remain unaffected.
Has the government finalised this policy? Not yet. An amendment removing the legal restriction on charging MDR has been passed, but the actual decision on rates and thresholds is expected to come later, from the NPCI-led UPI and Services Steering Committee, after the legislative process concludes.
One Thing You Can Do Right Now
Rather than reacting to every headline on this topic, bookmark the official Ministry of Finance or RBI press release page and check it directly whenever a new UPI-related claim shows up on your phone. That one habit will save you from a lot of unnecessary confusion as this policy discussion continues to unfold over the coming months.