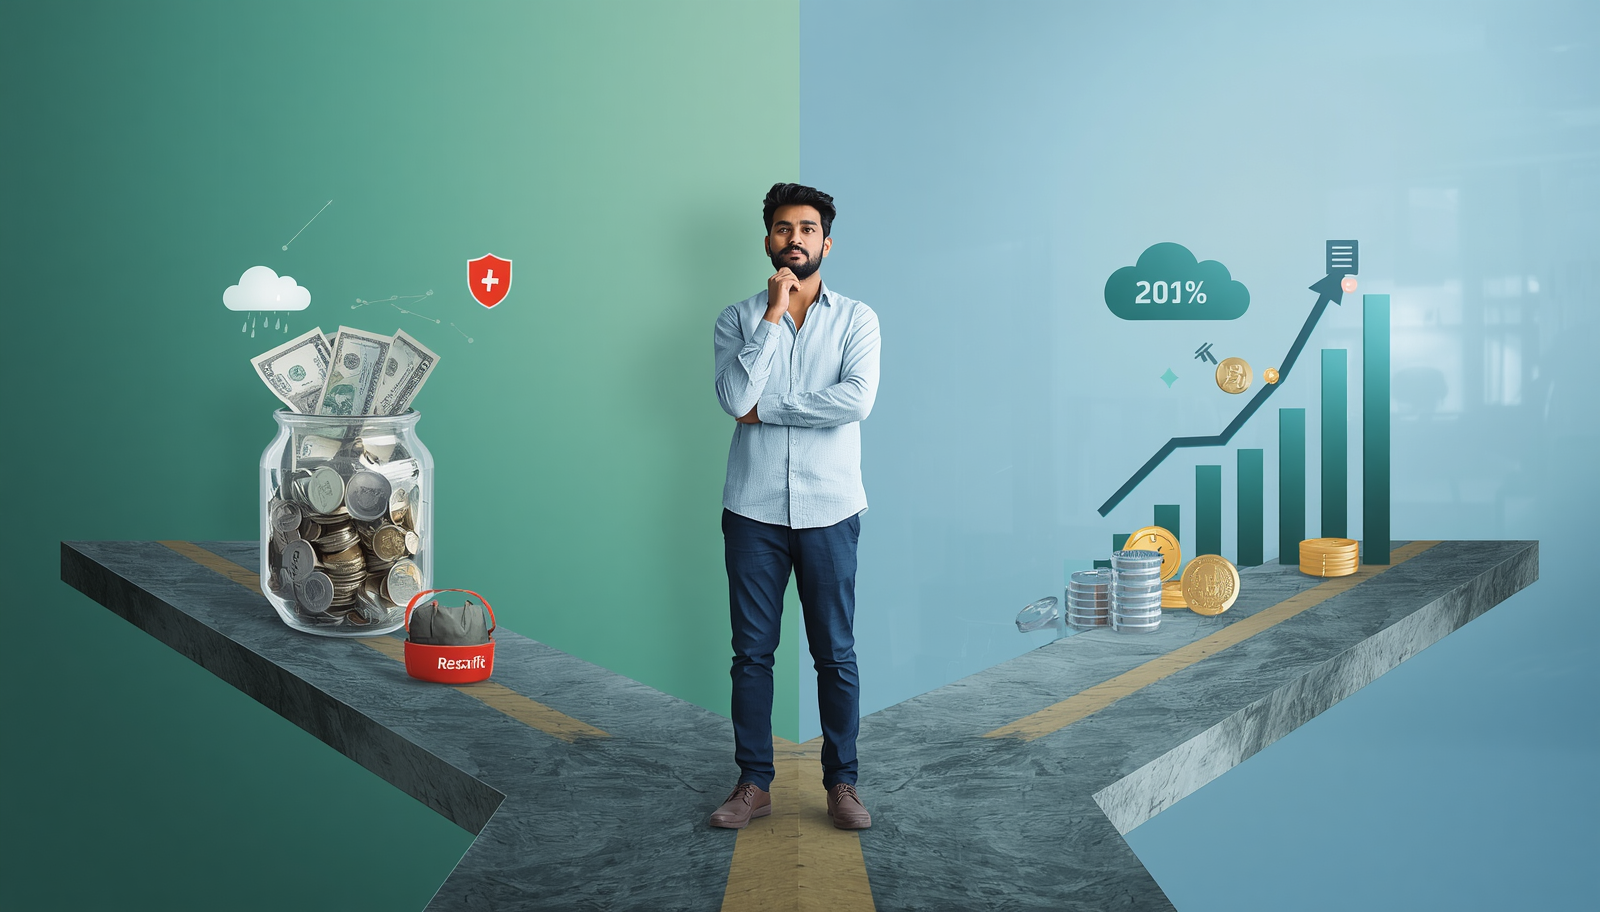
The moment your first salary hits your account, this question pops up: “Should I build an emergency fund first, or just jump straight into mutual funds and start investing?” It’s one of the most common dilemmas for anyone starting their financial journey, especially young earners in their first job.
Quick Answer: Build your emergency fund first save 3 to 6 months’ worth of monthly expenses before you start investing seriously. Without this cushion, a single bad month can force you to sell your investments at a loss, wiping out both your money and your peace of mind.
Let’s break this down properly so you understand not just what to do, but why it actually matters.
What Exactly Is an Emergency Fund?
An emergency fund is the money you set aside specifically to handle unexpected situations job loss, a medical emergency, sudden vehicle repairs, or a family crisis without having to borrow money or swipe a credit card in panic.
It’s not an investment. It’s not insurance either. Think of it as your financial cushion: money that’s safe, stable, and instantly accessible when life throws a curveball.
Who Needs This the Most?
- Freelancers and gig workers with irregular income
- Single-income households
- Anyone carrying a home loan or car loan
- People working in industries with less job stability
I remember a friend who went through this in 2020. He had a stable IT job, a decent salary, but zero emergency fund. When a sudden layoff hit, he had no cushion to fall back on. Over the next three months, he was forced to pause his SIPs and sell stocks at a loss just to cover basic expenses right when the market itself was down.
That one decision, made out of panic rather than planning, completely derailed his long-term investment strategy.
This is the real lesson here: investing without an emergency fund is like building a house without a foundation.
What Is Investment, and Why Does It Matter?
Investing means putting your money to work over time so it grows. Mutual funds, stocks, PPF, fixed deposits, gold — these are all common investment options for Indian households.
Here’s why investing matters:
- It beats inflation – money sitting idle in a savings account slowly loses purchasing power over the years
- It builds long-term wealth – essential for goals like buying a house, retirement, or your children’s education
- It benefits from compounding – starting early gives your money more time to grow
But investing is a long-term game. In the short term, markets can be volatile. That’s exactly why your emergency money should never be tied up in investments liquidity and safety come first for that portion of your finances.
Emergency Fund vs Investment: The Core Difference
| Factor | Emergency Fund | Investment |
|---|---|---|
| Purpose | Safety and quick access | Growth and wealth creation |
| Risk level | Very low | Depends on the instrument |
| Liquidity | High, immediate access | Varies by product |
| Time horizon | Short-term need | Long-term goal |
| Returns | Low (savings/liquid fund level) | Potentially higher over years |
These two serve completely different purposes. One protects you from risk, the other helps you build wealth. It’s not about choosing one over the other it’s about getting the sequence right.
So, What Should You Do First? A Step-by-Step Approach
Here’s a practical sequence that actually works in real life:
Step 1: Track Your Monthly Expenses
Before anything else, get clarity on your actual monthly spend rent, groceries, EMIs, utility bills, everything included.
Step 2: Start With a Small Emergency Buffer (1 Month)
Don’t wait until you’ve saved the full 6 months’ worth. Start with just one month’s expenses set aside in a savings account or liquid fund. Think of this as your “starter cushion.”
Step 3: Begin Small Investments in Parallel
Once you have that one-month buffer, start a small SIP even ₹500 or ₹1,000 a month is fine. You don’t need to wait for your emergency fund to be fully built before starting to invest. Doing both in parallel builds good financial habits early.
Step 4: Gradually Build Your Emergency Fund to 3-6 Months
As your salary increases or you receive bonuses, steadily grow your emergency fund until it covers 3 to 6 months of expenses. This becomes your primary safety net.
Step 5: Shift Into Serious Investment Mode
Once your emergency fund is solid, you can confidently scale up your investments increase SIP amounts, diversify across equity, debt, and gold, and start planning goal-based investments for the future.
Real-Life Scenarios: Two Different Approaches
Case 1 – Priya, 26, Marketing Executive: As soon as her salary started, Priya put nearly 70% of it directly into mutual funds. Eight months later, an unexpected medical expense came up. With no emergency fund to fall back on, she had to redeem her mutual fund units at a loss right when the market happened to be down.
Case 2 – Karthik, 27, Software Engineer: Karthik spent his first four months building a small emergency fund covering about 3 months of expenses. Only after that did he start his SIP. When a sudden bike repair came up, he used his emergency fund without touching his investments at all.
These two stories illustrate the same point: sequence matters more than speed.
Common Mistakes to Avoid
- Keeping your emergency fund in stocks (low liquidity, high risk)
- Putting your entire salary into investments with no safety buffer
- Treating a credit card limit as your “emergency fund” that’s debt, not savings
- Waiting to invest until your emergency fund is 100% complete this causes unnecessary delay in wealth building
Where Should You Keep Your Emergency Fund?
Your emergency fund needs to be safe and easily accessible. The best options are:
- A savings bank account
- Liquid mutual funds
- Short-term fixed deposits that allow easy withdrawal
High-return options like equity or long-term fixed deposits aren’t suitable for an emergency fund, because here, accessibility and stability matter far more than returns.
Frequently Asked Questions
1. How much should I keep in my emergency fund? A general rule of thumb is 3 to 6 months’ worth of essential monthly expenses. If you have significant family responsibilities, you might consider extending this to 6-9 months.
2. Should I wait until my emergency fund is complete before I start investing? No. Once you have even a small buffer (around one month’s expenses), you can start a small SIP in parallel. Build both gradually rather than waiting for one to finish before starting the other.
3. Can I keep my emergency fund in mutual funds? You can consider liquid funds specifically, since they carry low risk and allow easy withdrawal. Equity mutual funds are not suitable for emergency fund purposes due to market volatility.
4. Is it okay to just keep an emergency fund and skip investing altogether? That’s fine in the short term, but it won’t help you build wealth over the long run. Inflation gradually erodes the value of idle savings, so investing eventually becomes necessary for long-term financial growth.
Final Thoughts
An emergency fund and an investment portfolio are two different pillars of your financial life. One protects you when things go wrong, the other builds your future when things go right. Get the order right, and you avoid panic-driven decisions while steadily building real wealth over time.
Disclaimer: This article is written for general financial awareness and should not be considered personalized financial advice. For decisions suited to your specific situation, it’s advisable to consult a certified financial advisor.
If you’ve read this far, here’s your one action for this week: calculate your monthly expenses and open a simple liquid fund account that’s the real first step toward building your emergency fund.